Climate risks threaten property values: Insights from experts on prevention and insurance

Published
Subject
Event
Climate risks and climate adaptation of properties were the focal point on 19 May 2026, when Upsite invited property owners, managers, advisors, and investors to a professional morning event at Sea Level in Nordhavn.
The day offered concrete insights from three experts who, from their respective angles, put words to the same fundamental question: what does it cost not to act?
Climate change and properties: Water does not negotiate
Climate change does not just alter how much water comes. It changes when, how, and for how long. Cloudbursts and heavy precipitation, rising groundwater, storm surges, and coastal flooding are not future scenarios. They are today's reality, and they are already affecting the built environment from all sides.
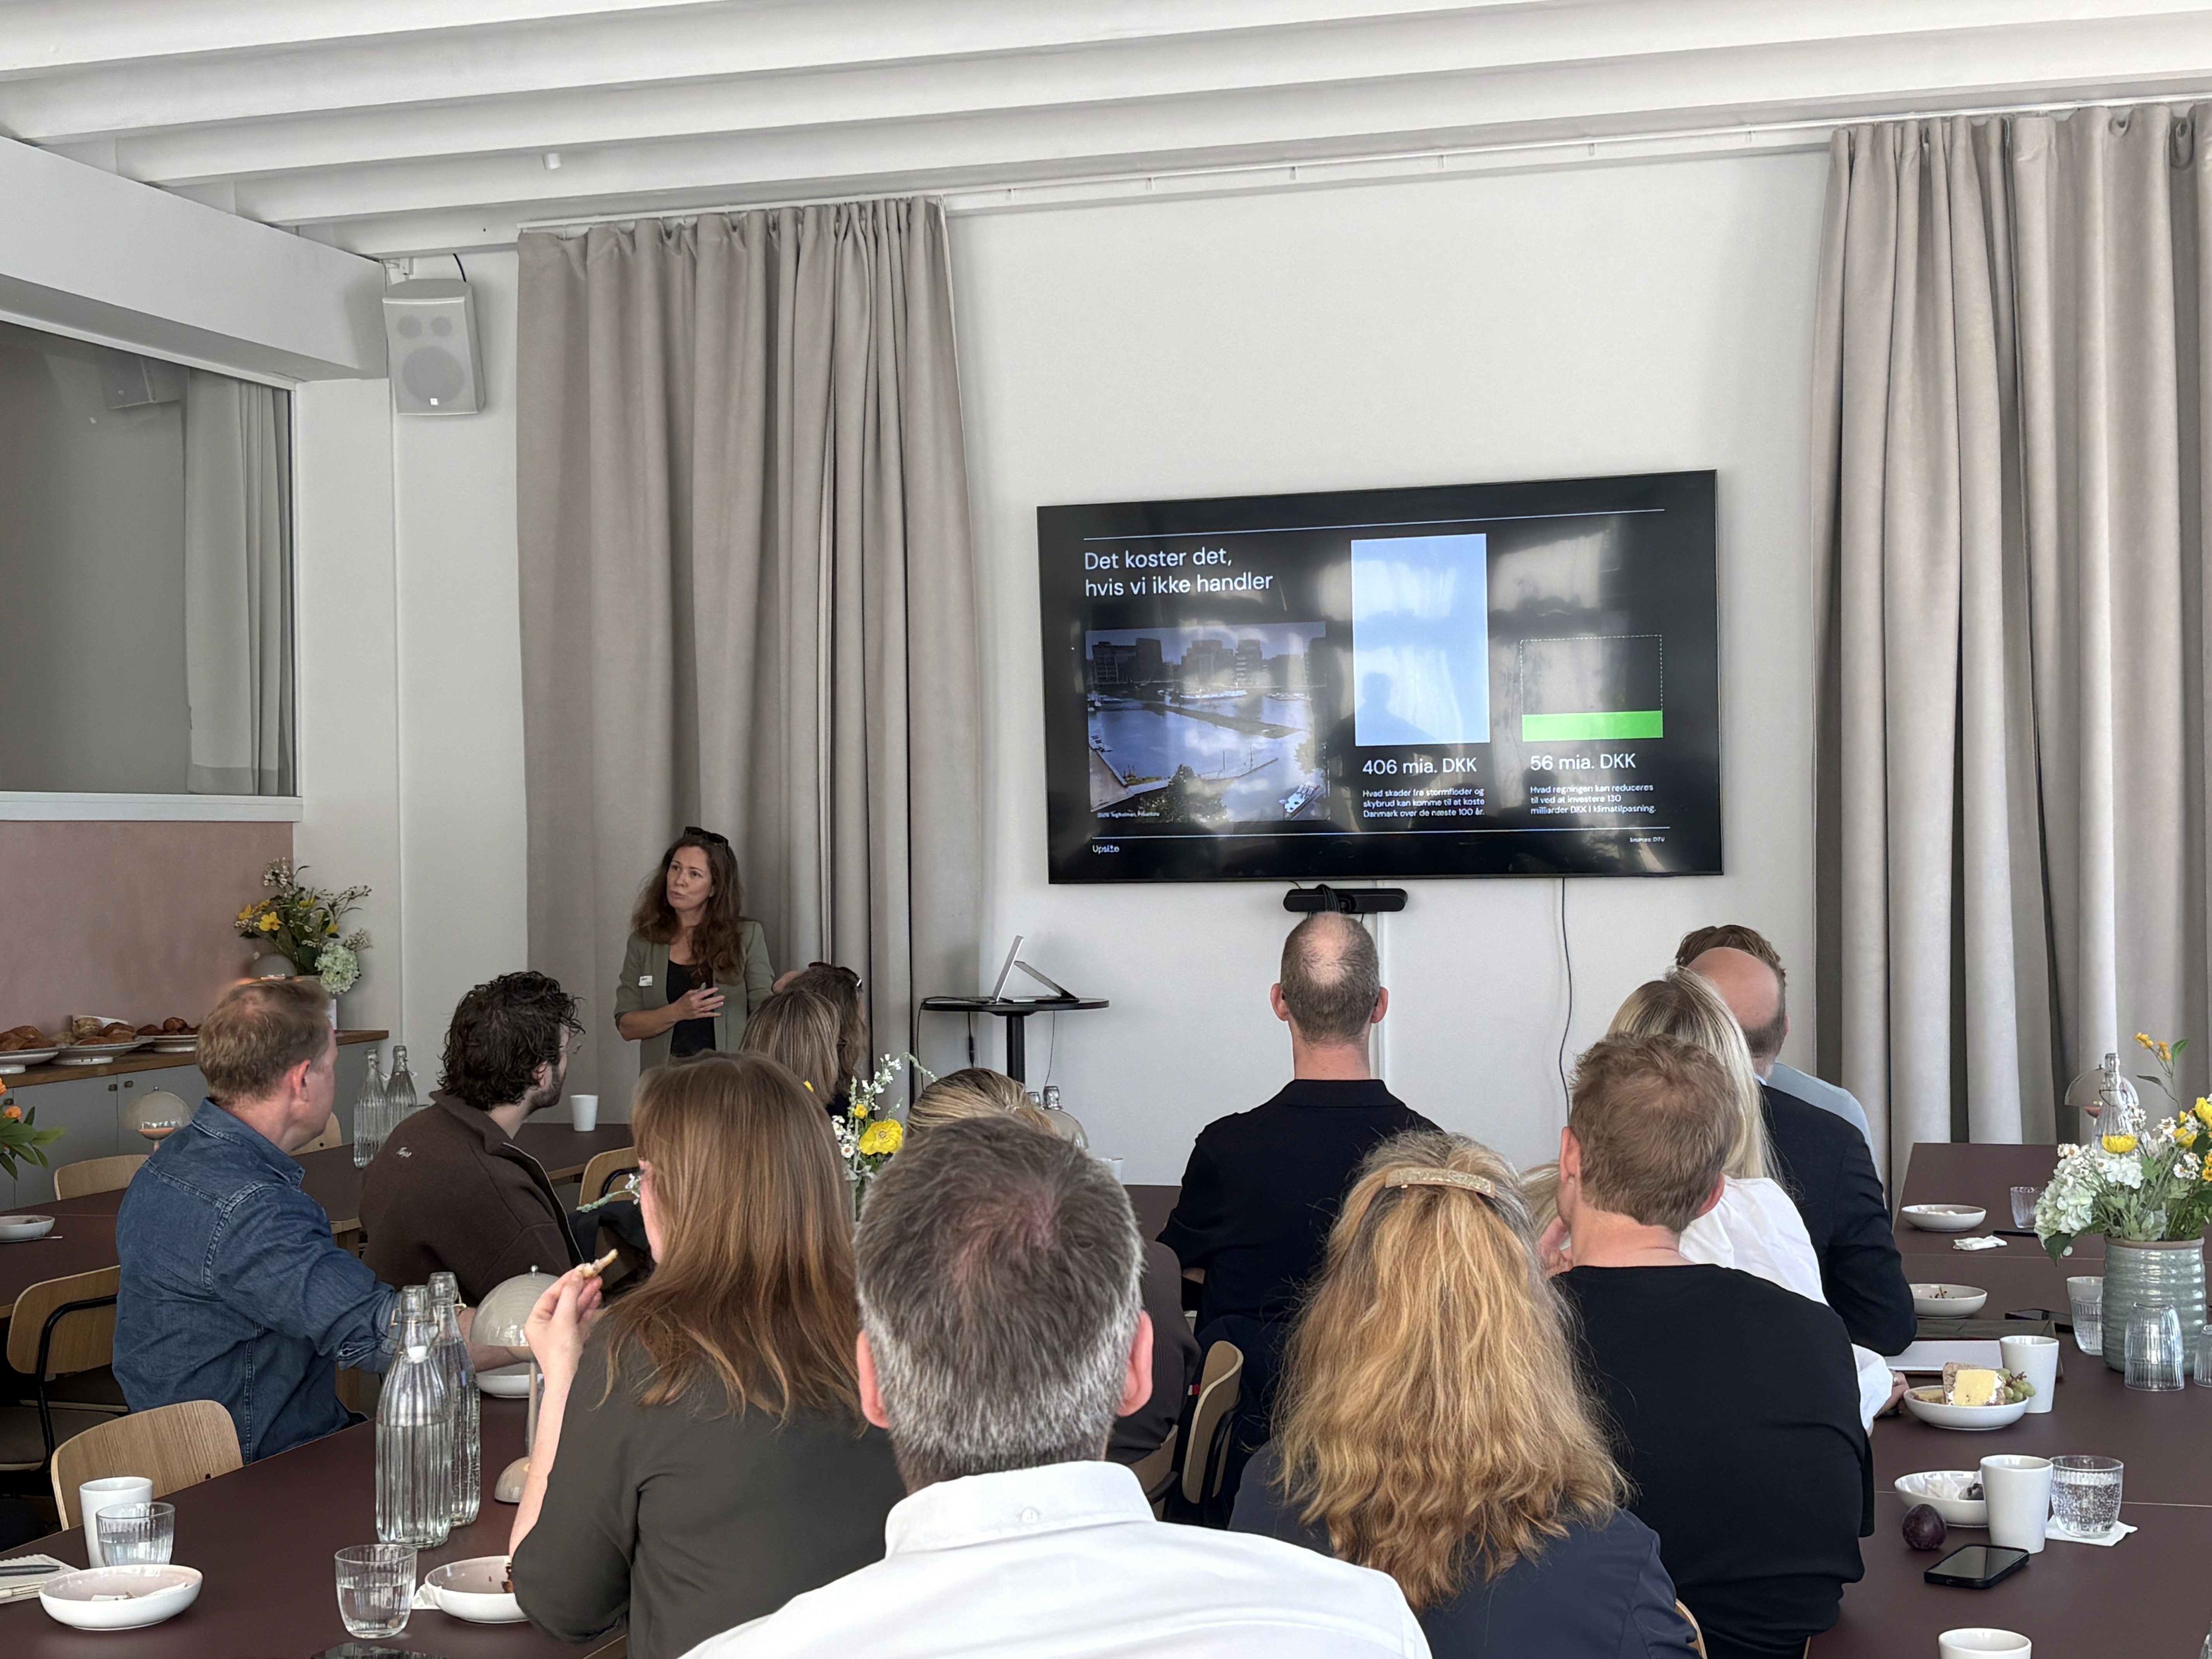
According to calculations from DTU, total damage to buildings, infrastructure, and businesses could run up to DKK 406 billion over the next 100 years without climate adaptation. If we invest DKK 130 billion in prevention, that bill can be reduced to DKK 56 billion. The numbers speak for themselves. Still, many property owners and managers lack a concrete and applicable basis for action. That was what the day attempted to provide.
Climate risk analysis for properties step by step
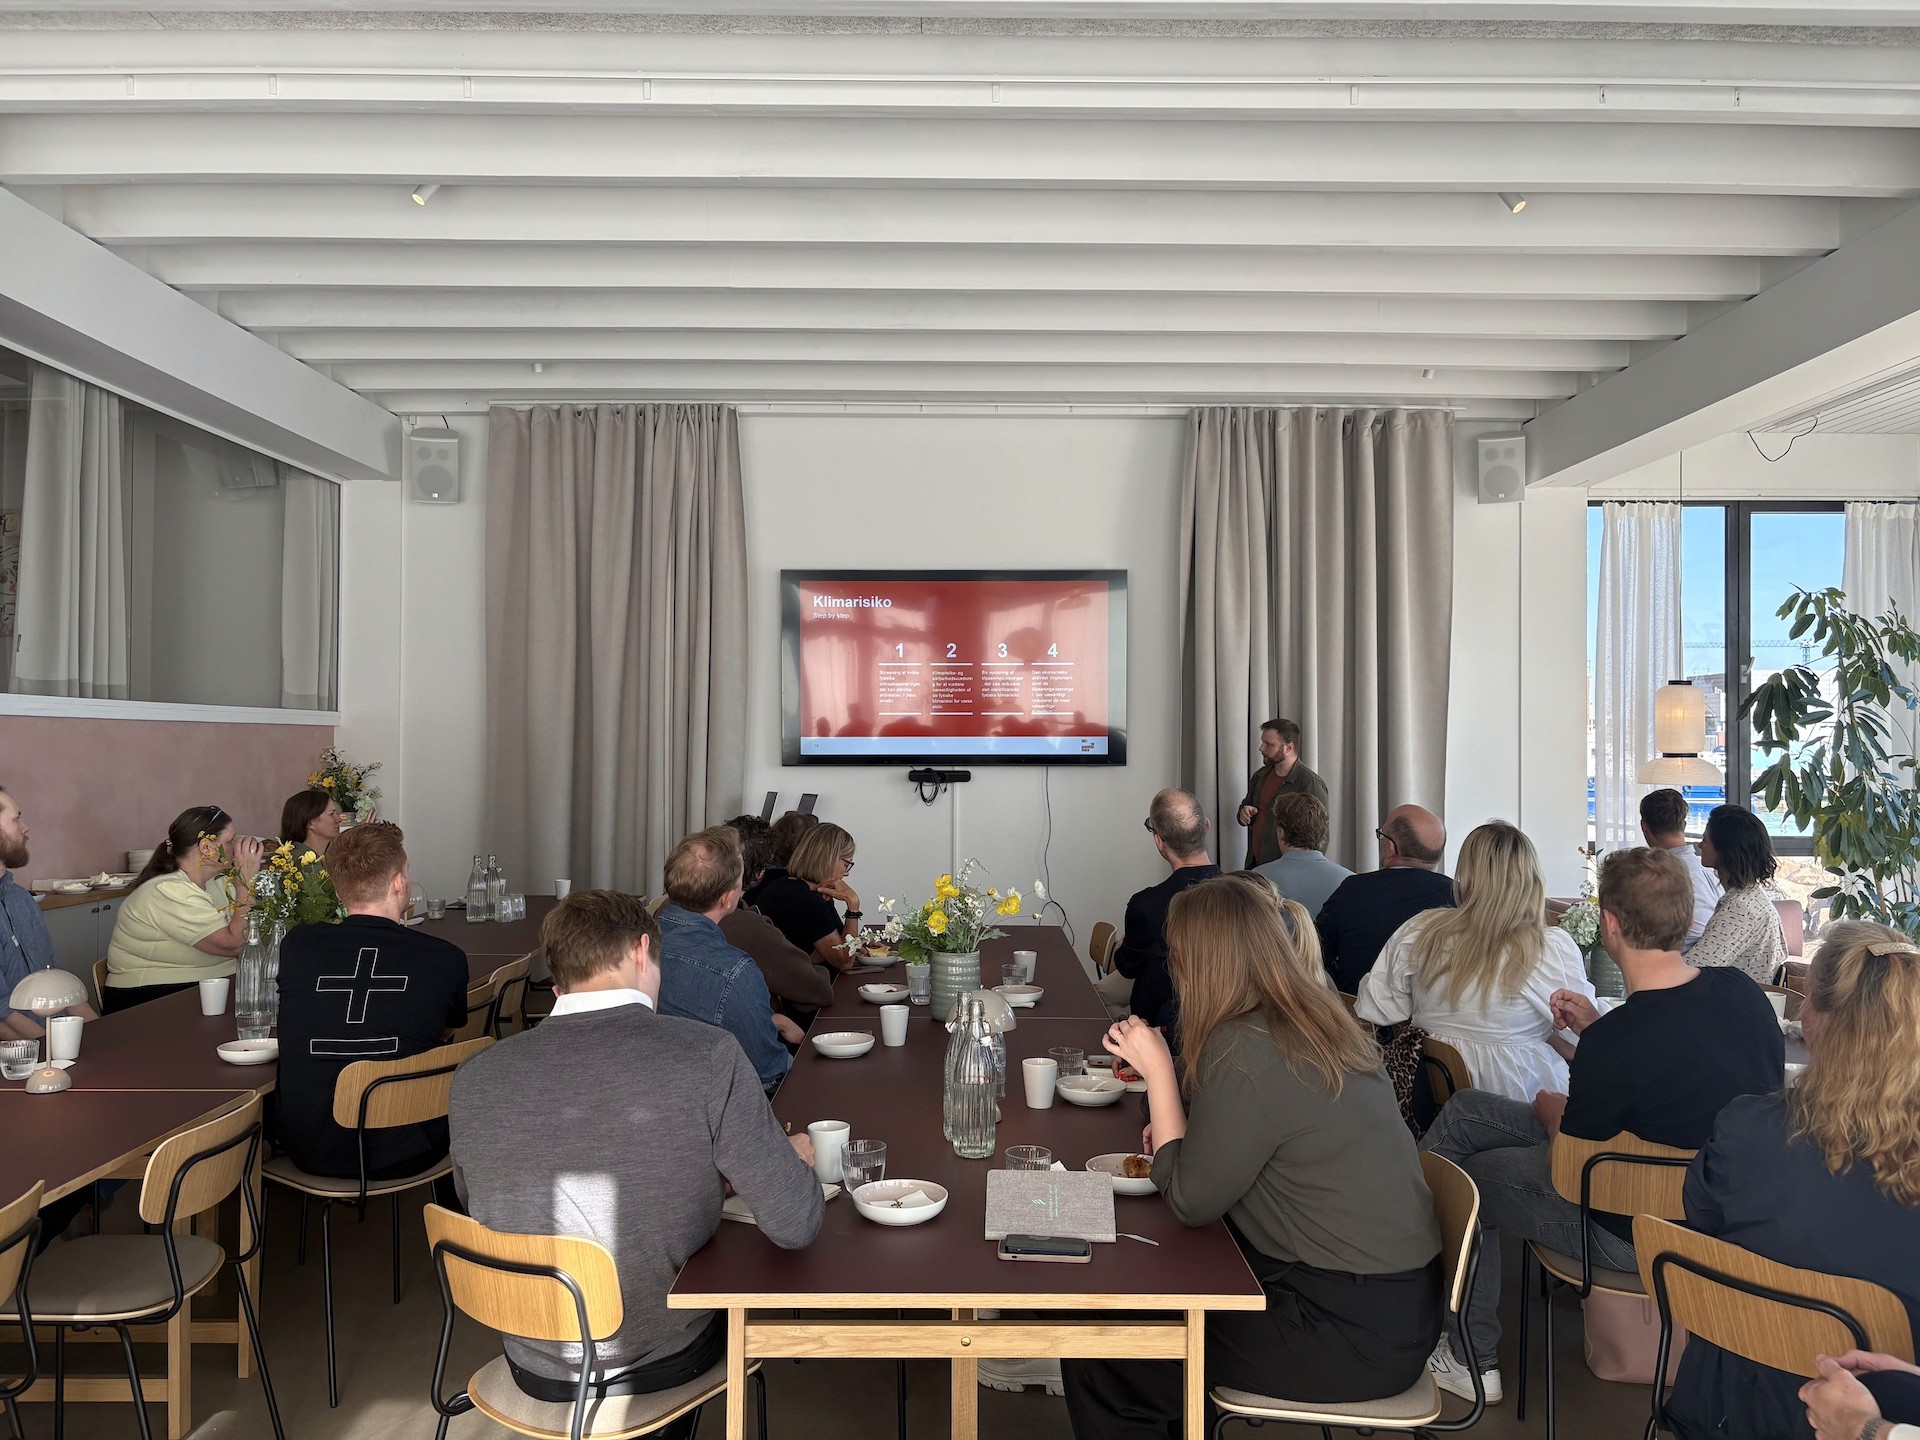
Mike Danielsen, Senior Sustainability Consultant from the Council for Sustainable Building, opened the day with a review of how to work systematically with climate risk analysis in practice. Based on the EU Taxonomy and the DGNB 2025 manual, he presented a four-step approach: screening of climate exposures, vulnerability and risk assessment, assessment of adaptation solutions, and final implementation.
A key message from Mike was that working with climate risks does not have to be overwhelming. The tools already exist: DMI Klimaatlas, KAMP, and Kystplanlægger.dk provide concrete data on a building's exposure, and the Council for Sustainable Building has published a guide to climate risk analysis that helps property managers and developers get started step by step.
At least as important is asking the right questions: Are there challenges now? Have there been previous problems with water damage? Are there particularly vulnerable parts of the building? And who will solve it if it escalates?
Insurance coverage for water damage: What does your policy actually cover?
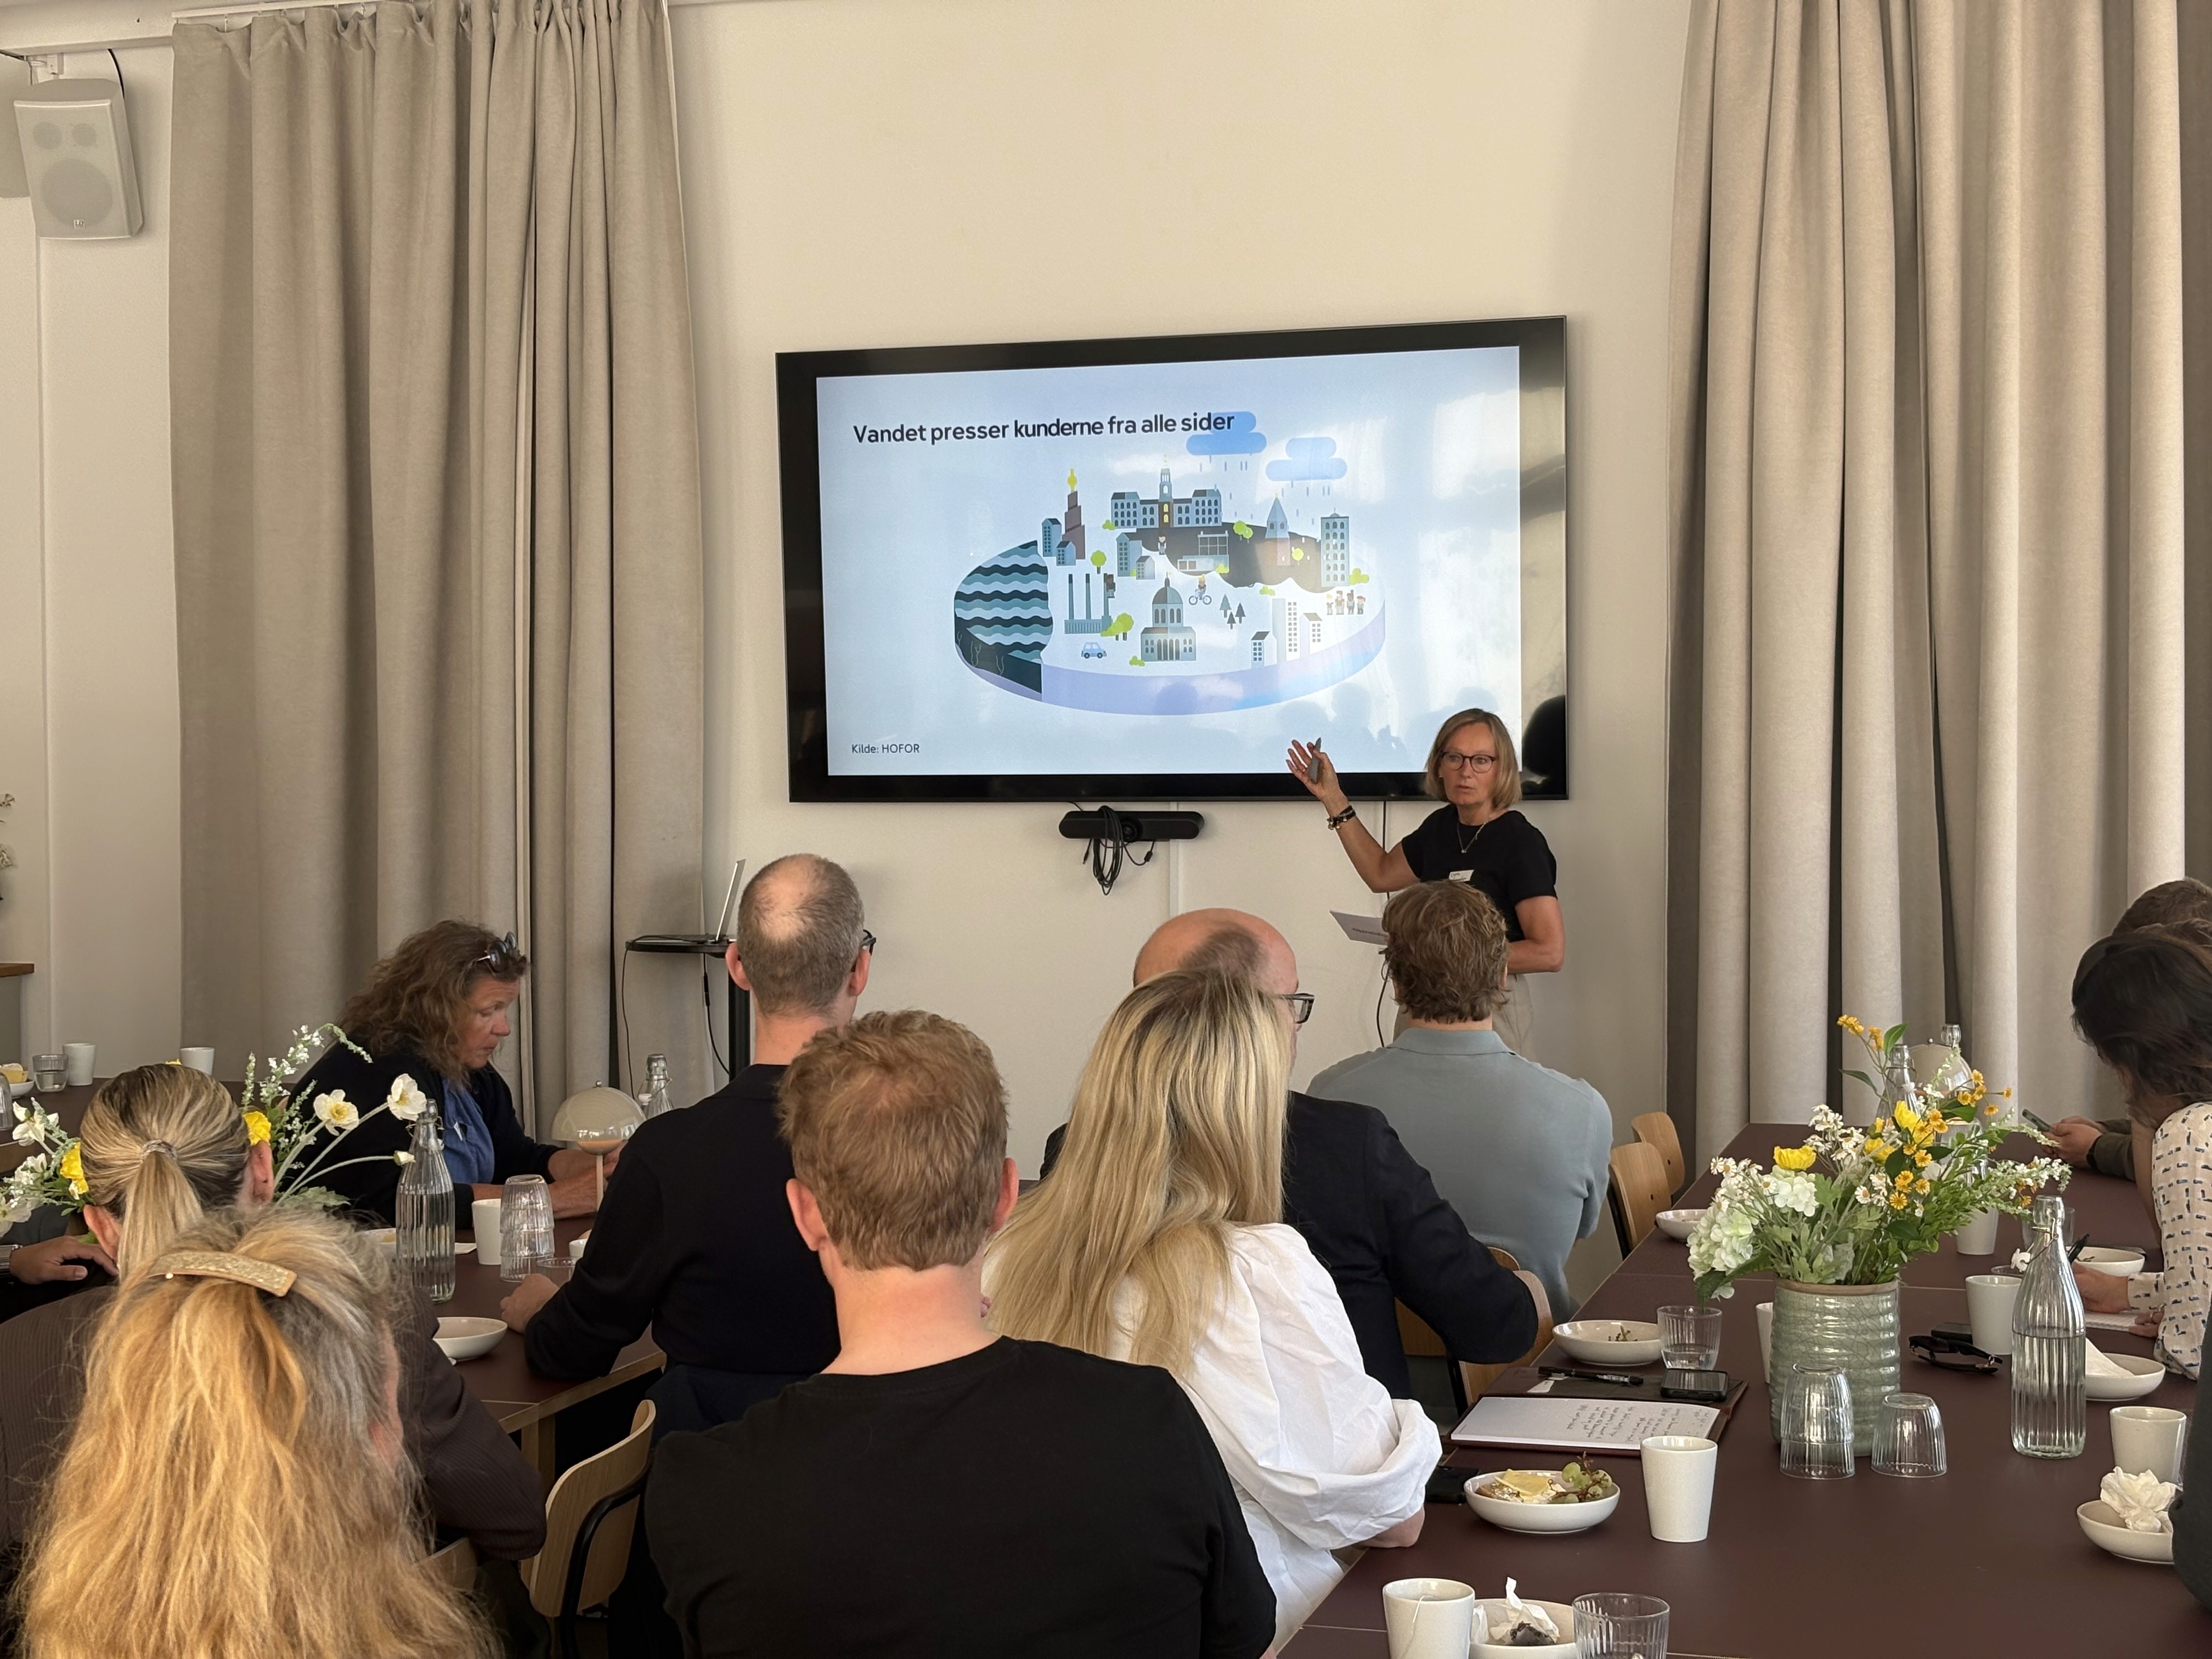
Lene Rasmussen, Claims Director at Gjensidige, gave the day an honest and concrete look at the possibilities and limitations of insurance in connection with climate-related water damage. Her message was clear: insurance is a safety net, not a solution to climate risks.
Water is pressing commercial properties from all sides: cloudbursts from above, storm surges from outside, and rising groundwater from below. And what is decisive for insurance coverage is not just whether you have a policy, but precisely where the water is coming from. For example, storm surge is not covered by commercial insurance, but by the public storm surge scheme, and groundwater and moisture are normally not covered at all.
With 300% more homes threatened by storm surges towards 2050 and rising insurance premiums in exposed areas, it is becoming increasingly crucial to know your actual coverage and work actively on preventing water damage. As Lene formulated it: beautiful materials do not help if the installations are still in the basement.
Prevention of water damage: The most expensive damage is the one no one saw coming
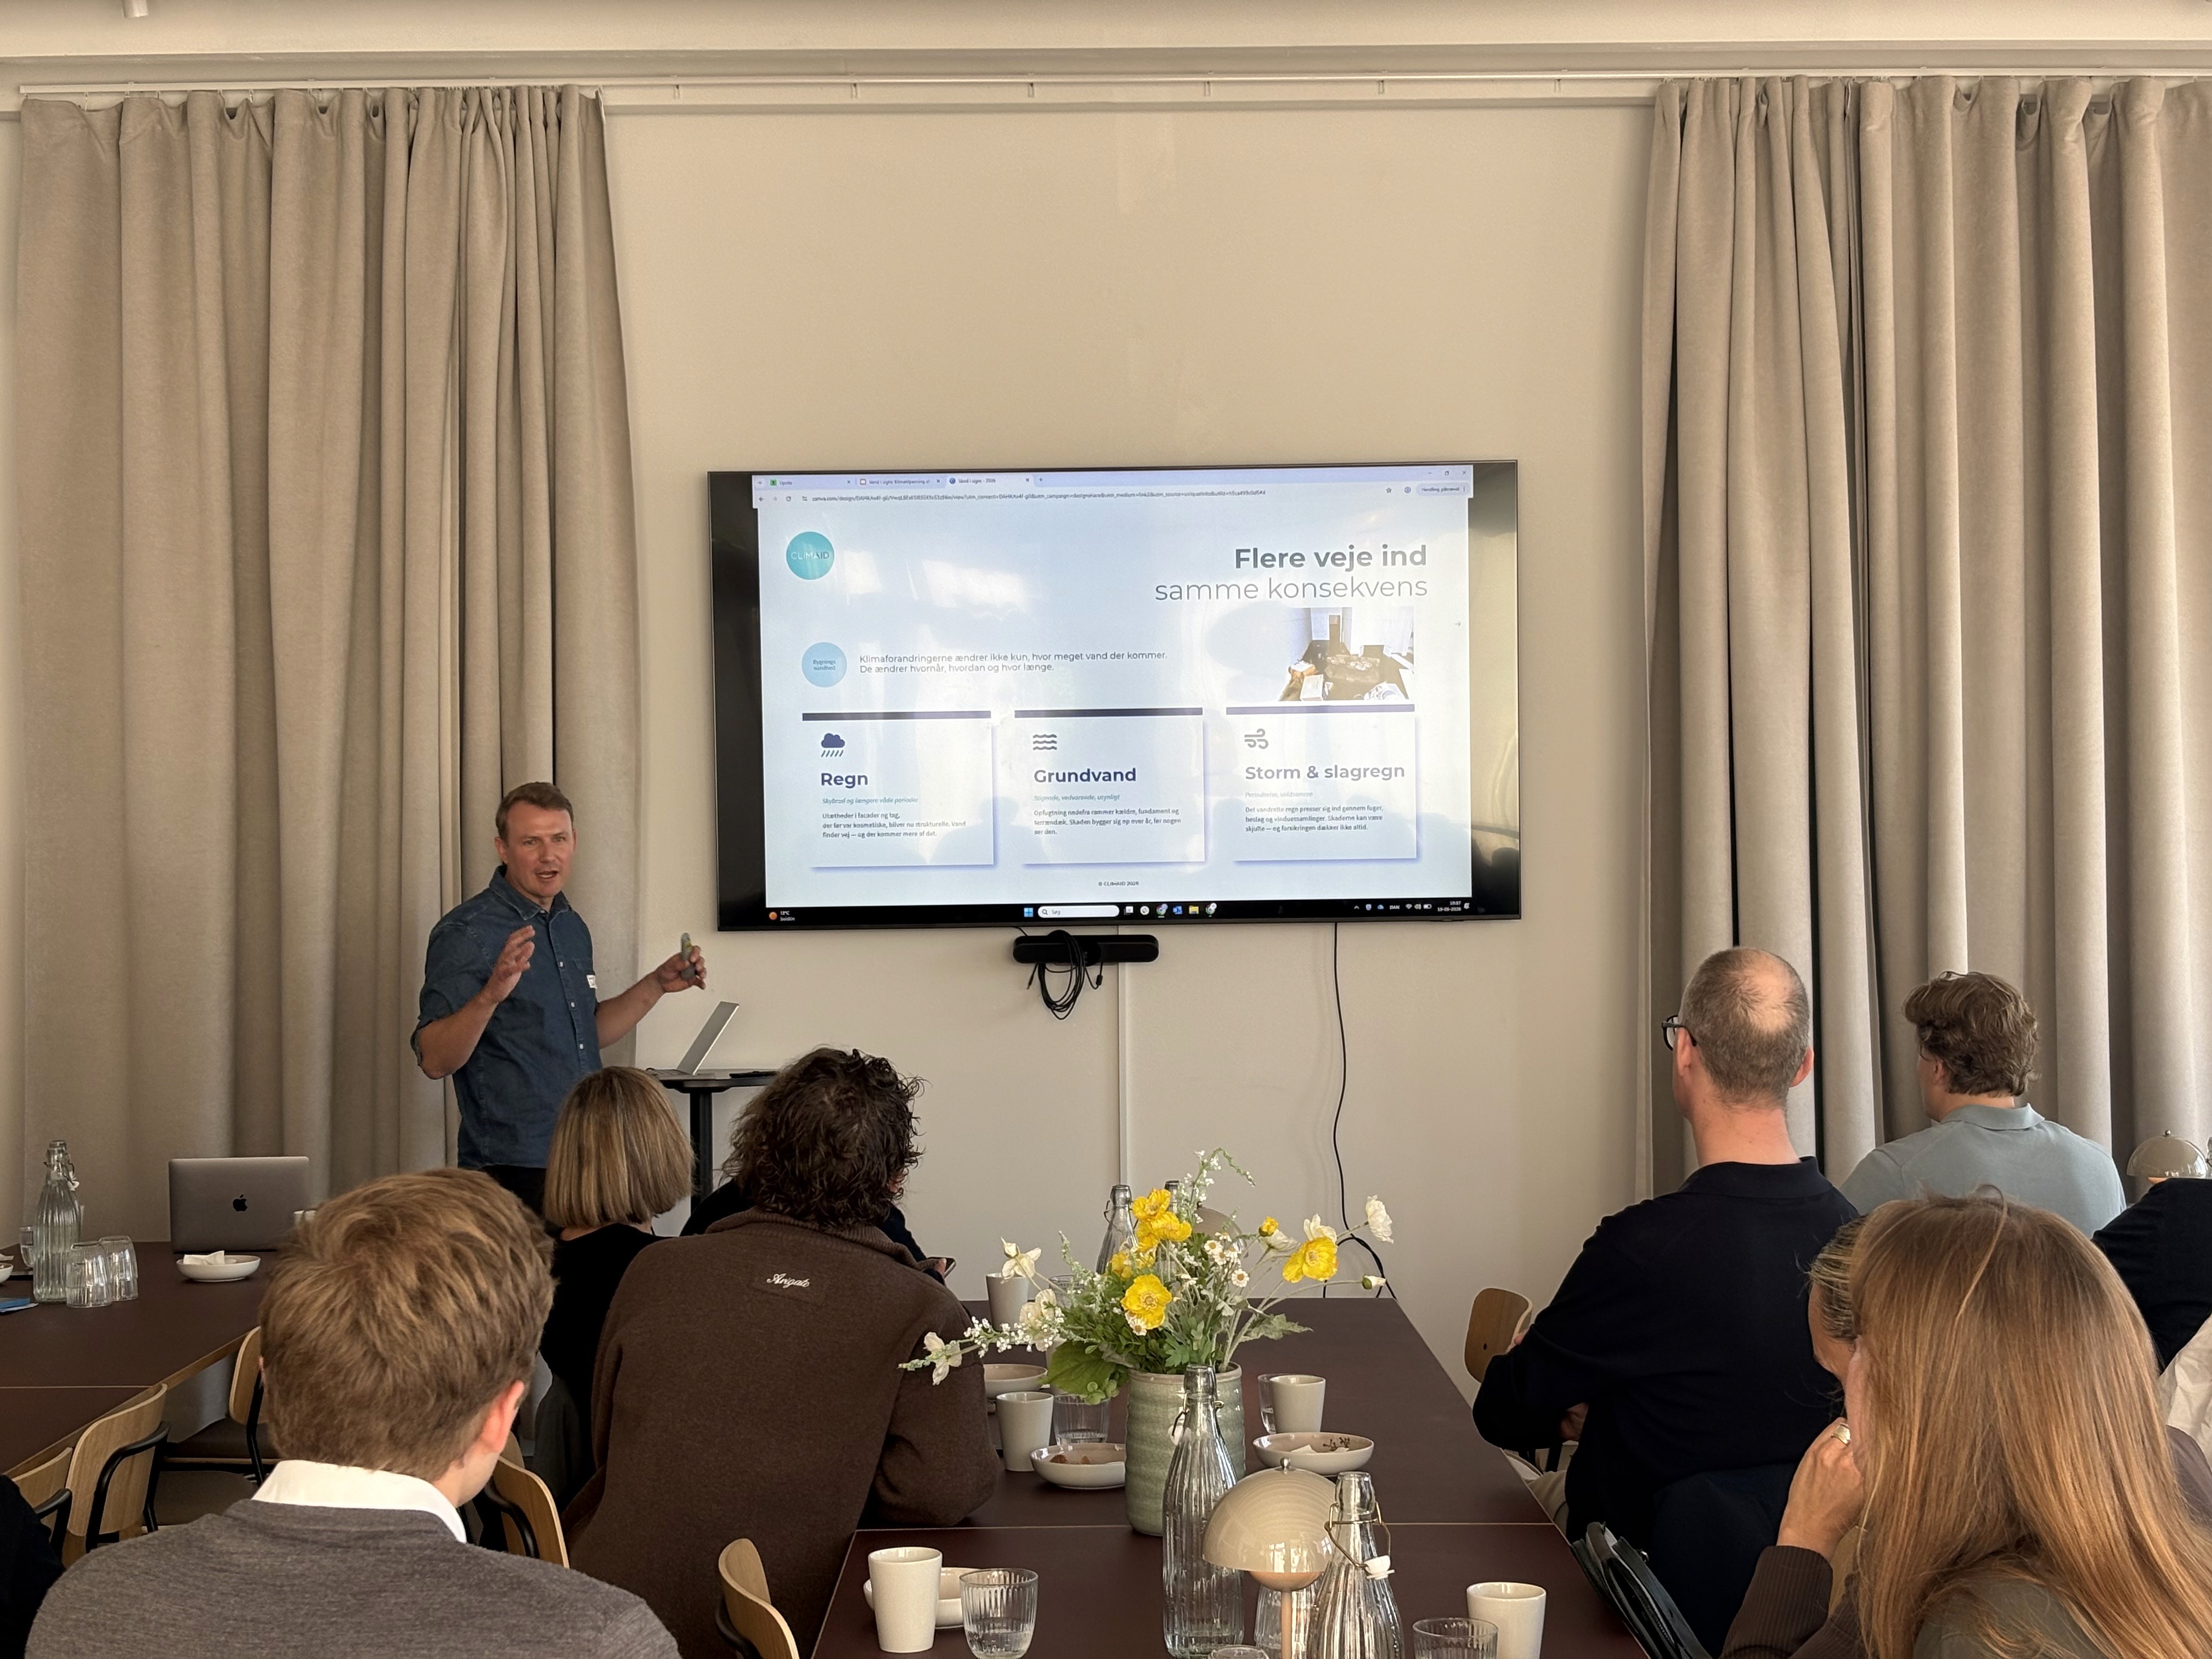
Kenneth Holck Jakobsen, CEO and Co-founder of CLIMAID, concluded the day with a perspective on what water damage on properties costs when not detected in time, and what technology can do to change that.
CLIMAID works with continuous, data-driven monitoring of building health: IoT sensors measure moisture, temperature, and water in real time, AI agents analyze data and warn of anomalies, and operations staff or damage control services can act before the damage becomes visible. The difference in cost between early detection and a fully escalated water damage is up to a factor of 300.
Kenneth also pointed to a dimension that is rarely discussed in the context of climate risks: the consequences for the residents. Dehumidification takes 4-8 weeks, mold is a health risk for almost one in five Danish homes, and rehousing is the part of the bill that does not appear on any insurance policy.
Climate adaptation of properties is not a choice, it is a prerequisite
The day showed that the industry is moving. It is no longer only the most forward-looking property investors who deal with climate risks. Legislation, financial institutions, and insurance companies are increasingly demanding documentation and action, and the consequences of waiting are already measurable today.
The most important message across all three presentations was the same: preventing climate risks makes a real difference for both property values and operating economy, and it is easier to act when you are informed.
Read also: Future-proofing properties: Insights from event on climate risks